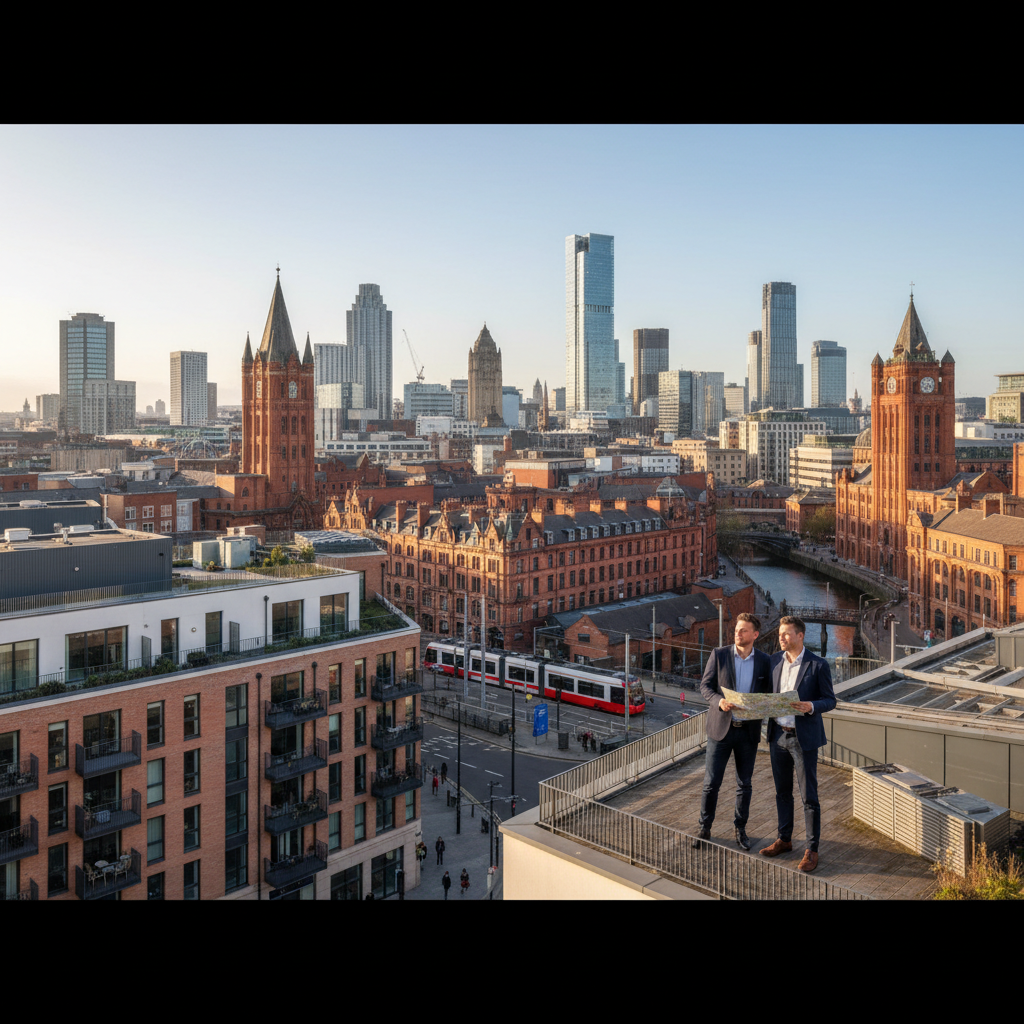
Manchester is regularly cited as one of the strongest short-let markets outside London, and the investor interest has followed. But enthusiasm and profitability are different things, and plenty of hosts have entered the Manchester market with unrealistic figures in their heads. This post lays out what the market actually looks like, where the opportunities are sharpest, and where operators tend to come unstuck.
Why Manchester attracts short-let investors
Manchester has a combination of demand drivers that most UK cities simply cannot match. It has two Premier League football clubs drawing visitors almost every other weekend from August through May. It hosts a near-constant rotation of arena concerts at the AO Arena, one of the busiest indoor venues in Europe. The city centre has seen more than £4 billion of commercial and residential development since 2015, and the business travel market — particularly around MediaCityUK in Salford — adds a layer of midweek demand that keeps occupancy steady rather than weekend-only.
Then there is the student and academic ecosystem. With the University of Manchester, Manchester Metropolitan and Salford University between them enrolling well over 100,000 students, families visiting for graduations, open days and term-start weekends create predictable demand spikes that experienced operators learn to price around. Add in the fact that Manchester Airport is the third busiest in the UK, and you have a city where short-let demand comes from multiple directions at once rather than depending on a single sector.
What can you realistically earn on Airbnb in Manchester?
A well-managed one-bedroom apartment in the city centre — think Ancoats, the Northern Quarter or Deansgate — will typically generate between £1,800 and £2,400 per month in gross revenue when occupancy is running at 75–85%. A two-bedroom in the same areas can push £2,800 to £3,500 per month at peak performance. These are not cherry-picked best-case figures; they reflect what consistently well-reviewed, professionally managed listings achieve over a full calendar year including quieter January and February periods.
The ceiling is meaningfully higher on event weekends. A two-bedroom apartment near the Etihad or Old Trafford on a derby weekend or a Champions League fixture can command £400 to £600 per night, and the AO Arena effect lifts rates across a wide radius on concert dates. Where operators leave money on the table is by setting static pricing and missing these windows entirely — or, on the other side, by pricing too aggressively on quieter weeks and sitting empty. Dynamic pricing discipline is what separates average performers from top-quartile ones in this market. You can read more about how we approach this on our pricing page.
For context, a comparable one-bedroom apartment in Manchester city centre renting long-term would achieve roughly £1,100 to £1,350 per month at current market rates. The short-let premium — after management fees, cleaning, utilities and platform costs — typically leaves operators with a net income 30 to 50% above what a standard AST tenancy would return. That gap narrows during void periods and widens during peak demand, which is why understanding the local calendar matters so much.
The best areas in Manchester for short-let properties
Not all of Manchester performs equally. Ancoats has emerged as the city's strongest short-let postcode over the past four years. Its restaurant and bar scene — Rudy's Pizza, Elnecot, the Blossom Street strip — means guests actively seek it out rather than treating it as a convenient location by default. The regeneration of the New Islington marina area has added further appeal. One-bedroom apartments here consistently outperform equivalent units in older city centre blocks by 10 to 15% on both nightly rate and occupancy.
Deansgate and Castlefield attract a slightly different guest profile — more corporate, more couples celebrating occasions — and command premium rates for well-presented units. Castlefield in particular benefits from its canal-side setting, which photographs exceptionally well and justifies rates that might otherwise seem high for the square footage. Spinningfields sees strong corporate demand but can be slower at weekends, so the revenue profile is more even but less spikey than event-driven areas.
Salford Quays and MediaCityUK is underrated by many investors who default to M1 and M2 postcodes. The BBC, ITV and a dense cluster of production companies have created a permanent pool of short-stay workers — producers, contractors, film crews — who prefer an apartment over a hotel for stays of four to fourteen nights. This guest type is lower maintenance, leaves better reviews on average, and creates mid-week base occupancy that event-led areas sometimes lack.
Areas to approach with more caution include some of the further-out regeneration zones — parts of Hulme, Ardwick and sections of the Oxford Road corridor — where new apartment supply has outpaced short-let demand. High listing density in a low-demand micro-location is a reliable recipe for weak occupancy regardless of how good the property looks.
Occupancy rates and seasonality: what to expect
Manchester's seasonality is flatter than many UK cities, which is one of its genuine structural advantages. The football season alone provides a drumbeat of high-demand weekends that runs from early August to mid-May, covering almost the entire calendar year. This is not something you get in, say, a coastal market where you are heavily dependent on a June-to-August window.
From our experience managing properties across the city, annual occupancy for a well-positioned and well-managed Manchester city centre apartment sits at 72 to 82%. January is the soft month — corporate travel slows post-Christmas and there are fewer leisure reasons to visit — but it rarely falls below 55 to 60% for a decent listing, especially if you are pricing competitively for the month and targeting longer stays. One tactical move that works well in January is shifting minimum stay requirements down to two nights and targeting domestic weekend city-breakers, who are more price-sensitive than the summer crowd but still fill the calendar.
Costs, regulations and what operators get wrong
The cost structure of a Manchester short-let is not dramatically different from other major UK cities. Management fees for a full-service operator typically run at 18 to 25% of gross revenue. Cleaning costs per turnover for a one-bedroom apartment run at £55 to £80 depending on the provider and standard required. Utilities — electricity, gas, Wi-Fi — add roughly £150 to £200 per month depending on usage patterns, and it is worth noting that short-let guests use significantly more energy per night than long-term tenants.
On the regulatory side, Manchester currently falls under the same national framework as the rest of England. There is no city-wide short-let registration scheme in force as of mid-2025, though the government's broader short-term lets consultation is progressing and local councils in Greater Manchester have been vocal about housing pressure in certain districts. The planning use class position — specifically whether a property tipping over 90 days of short-let use per year requires a change of use from C3 to C5 — is an area where professional advice is essential, as enforcement postures vary and the rules are still bedding in. Always seek advice from a qualified planning consultant or solicitor for your specific property and situation.
The most common operational mistake we see in the Manchester market is over-estimating nightly rates based on peak-weekend comps and then being caught out when mid-week occupancy is poor. Running a profitable short-let in Manchester is not about maximising every nightly rate in isolation — it is about managing the blend of rate and occupancy across the full month. A host who achieves £120 per night at 85% occupancy will consistently outperform one achieving £160 per night at 55% occupancy, which sounds obvious until you are looking at your own listing and tempted to hold out for a higher price.
Leasehold restrictions: many Manchester city centre apartment blocks have head leases that prohibit or restrict short-term letting. Check before you buy, not after.
Mortgage terms: standard residential mortgages do not permit short-let use. You will need either a specific short-let mortgage product or a commercial mortgage, and the rates differ meaningfully.
Is Manchester the right market for you?
Manchester is a strong market for short-let investment, but it rewards operators who go in with accurate numbers and a clear area strategy. It is not a market where you can pick any city centre apartment, list it at an optimistic price, and expect the demand to paper over operational gaps. The competition from professionally managed listings has increased significantly since 2021, and guest expectations around quality, photography and responsiveness have risen with it.
If you already own a Manchester property and are weighing up short-let against long-let, the maths generally favour short-let for well-located city centre units, particularly one and two-bedrooms in Ancoats, Castlefield, the Northern Quarter and Salford Quays. For properties further from the core, the calculus changes and a long-let may actually produce a better risk-adjusted return once you account for higher void risk and longer turnaround times. Our Manchester property management team works across all these areas and can give you a grounded view of what a specific property is likely to achieve.
For investors comparing cities, Manchester consistently sits alongside Birmingham and Liverpool as one of the three most compelling regional short-let markets in England. Each has its own demand profile and risk characteristics, and the right choice depends as much on purchase price and yield entry point as it does on gross revenue potential.
If you want to know what a specific Manchester property could earn as a short-let, Truestays offers a free, no-obligation income estimate based on real local data rather than platform-generated projections. Get in touch with the team and we will give you an honest figure.
Ready to get started?
Get a free personalised income estimate for your property. No commitment, no pressure.